Fixed annuities have never been more relevant. In 2024, fixed annuity sales hit record highs, reflecting a large change in how Americans are thinking about protecting their money while still giving it room to grow. More than ever are picking annuities as a core part of their retirement strategy - and more than ever are grappling with which type actually fits their situation.
At their core, MYGAs and FIAs are designed to keep your principal safe and deliver steady, tax-deferred growth. But they go about it in meaningfully different ways. A MYGA locks in an interest rate for a set number of years - easy, predictable, no surprises. A fixed indexed annuity ties your possible growth to a market index like the S&P 500, with built-in protections that keep you from losing money when markets fall. Same large goal, different engines.
Choosing between them isn't about which one is better in the abstract - it's about which one is better for you with your timeline, your income needs, your comfort with complexity, and what you're actually trying to accomplish. What follows breaks down how each product works, what the trade-offs look like, and how to think through the choice.
Key Takeaways
- MYGAs offer fixed, predictable returns; FIAs link growth to a market index with downside protection but capped upside.
- Both products grow tax-deferred and protect principal, but differ significantly in certainty versus growth potential.
- Surrender charges typically span six to eight years; early withdrawals beyond the 10% free withdrawal allowance can be costly.
- Higher advertised MYGA rates from lower-rated carriers carry added risk, since annuities aren't FDIC-insured.
- MYGAs suit savers wanting simplicity and certainty; FIAs better fit those with longer timelines comfortable with complexity.
How MYGAs and Fixed Indexed Annuities Actually Work
A Multi-Year Guaranteed Annuity, or MYGA, works quite like a bank CD. You lock in a fixed interest rate for a set term - say, 3, 5, or 7 years - and your money grows at that rate no matter what the market does. At the end of your term, you'll know exactly what you'll have.
A Fixed Indexed Annuity, or FIA, takes a different approach. Instead of a fixed rate, your growth is linked to the performance of a stock market index like the S&P 500. You don't invest directly in the market, so you're protected from losses. But there's a trade-off: your gains are capped, which means you won't capture the full upside either.
A helpful way to remember it is to ask if you'd know what you'll earn, or have a shot at earning more with a ceiling on gains. Neither answer is wrong - it just depends on what you need from your money.
| Feature | MYGA | Fixed Indexed Annuity |
|---|---|---|
| Growth type | Fixed interest rate | Linked to an index |
| Market exposure | None | Indirect only |
| Can you lose money? | No | No (floor protection) |
| Is growth capped? | No | Yes, typically |
| Predictability | High | Moderate |
| Growth potential | Fixed and known | Variable, index-dependent |
Both products grow tax-deferred and are designed for long-term savings. The core difference is about certainty versus potential, and that's worth sitting with before going any further. You can learn more about your options through our fixed income annuities page, or reach out to our team to talk through what fits your situation.
Current Rate Landscape and What It Means for Your Decision
As of mid-2026, top MYGA rates from A-rated carriers range from around 5.00% on two-year contracts to about 5.65% on seven-year terms; it's an actual return for a product, and it holds up well against most alternatives in the fixed income space.
Some lower-rated carriers are advertising rates as high as 7.65% on 10-year contracts. That number is attractive. But the financial strength behind it might not be. A carrier's credit rating matters quite a bit here because your money is backed by that company's ability to pay - not by FDIC insurance - so it's worth a few minutes to check ratings from AM Best or S&P before getting drawn in by the headline number.
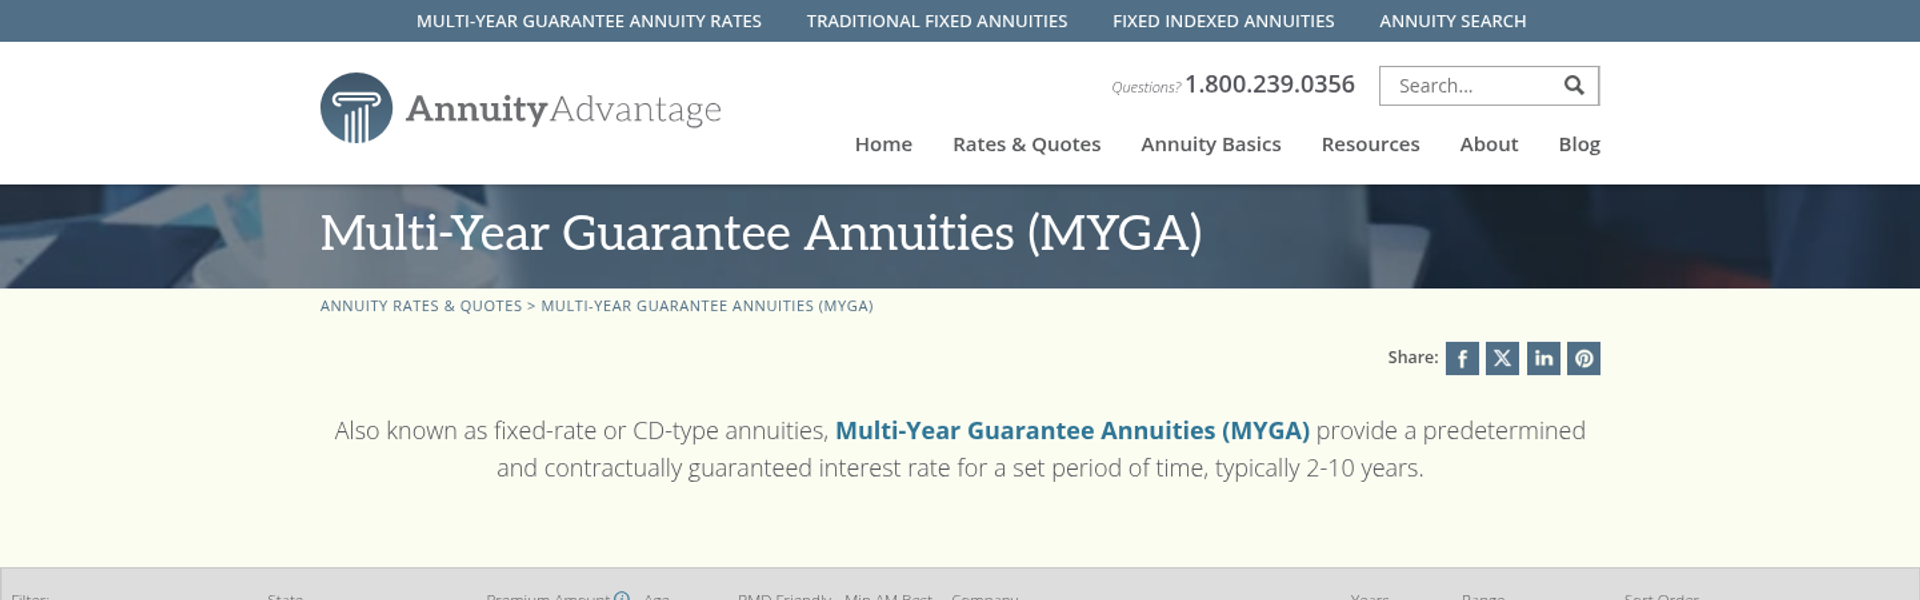
The wider rate environment also factors into what you can get from a Fixed Indexed Annuity. When interest rates are higher, insurers can afford to set more generous participation rates and caps on index-linked strategies; it's the environment we're in now, which makes FIA terms somewhat more competitive than they were a few years ago.
Projections place the 10-year Treasury in the mid-4% range through 2028. That context matters because MYGA rates are closely tied to longer-term bond yields. If those yields stay elevated, rates should remain historically interesting for a while longer. Our Coverage Corner has additional guidance on navigating these decisions.
| Product Type | Term | Approximate Rate (Mid-2026) | Carrier Rating Note |
|---|---|---|---|
| MYGA | 2-year | ~5.00% | A-rated carriers |
| MYGA | 7-year | ~5.65% | A-rated carriers |
| MYGA | 10-year | Up to 7.65% | Lower-rated carriers |
| FIA | Varies | Index-linked (no fixed rate) | Caps/participation vary by carrier |
The rate environment can make one product look more desirable than the other at a given moment. Just make sure a strong rate isn't the only thing you're looking at.
Surrender Charges, Liquidity Rules, and the Fine Print That Trips People Up
Both products lock your money up for a set period, and that's where people make expensive mistakes. Surrender charges on MYGAs usually run six to eight years, and FIAs can match or exceed that window. Withdrawing more than your contract allows during that time means paying a percentage of the amount you pull out.
Most contracts do include a free withdrawal provision, usually around 10% of your account value per year. That gives you some flexibility. But it's not the same as having liquid savings. If you need a large sum mid-contract, the math can get painful fast.
A common surrender charge schedule declines over the life of a contract as shown below.
| Contract Year | Typical Surrender Charge |
|---|---|
| Year 1 | 8% |
| Year 2 | 7% |
| Year 3 | 6% |
| Year 4 | 5% |
| Year 5 | 4% |
| Year 6 | 3% |
| Year 7 | 2% |
| Year 8 | 1% |
Actual schedules can vary by insurer and product, so always read your contract closely. Some FIAs have longer surrender periods than the table above shows.
Be honest with yourself here. If there's a chance you'll need a chunk of that money in the next few years, a long surrender window is a problem worth considering before you sign anything. Working with an experienced team of insurance professionals can help you evaluate whether the terms actually fit your situation.
Some contracts also have waiver provisions for things like nursing home stays or terminal illness diagnoses. These can soften the restriction. But they have their own conditions and don't apply universally. If you're weighing your broader coverage needs alongside retirement income planning, it's worth exploring the full range of insurance services available to you.
Tax Treatment, Inheritance, and the Details Most People Overlook
Both MYGAs and FIAs grow tax-deferred, which means you don't pay taxes on the gains each year - only when you take money out; it's a genuine benefit over a standard savings account or CD. But the tax picture gets more layered depending on how the account is funded.
A qualified annuity is funded with pre-tax money, like a rollover from a 401(k) or traditional IRA. When you take withdrawals, the full amount is taxable as income. A non-qualified annuity is funded with after-tax money, so only the growth portion is taxed on the way out - this distinction matters quite a bit when planning withdrawals.
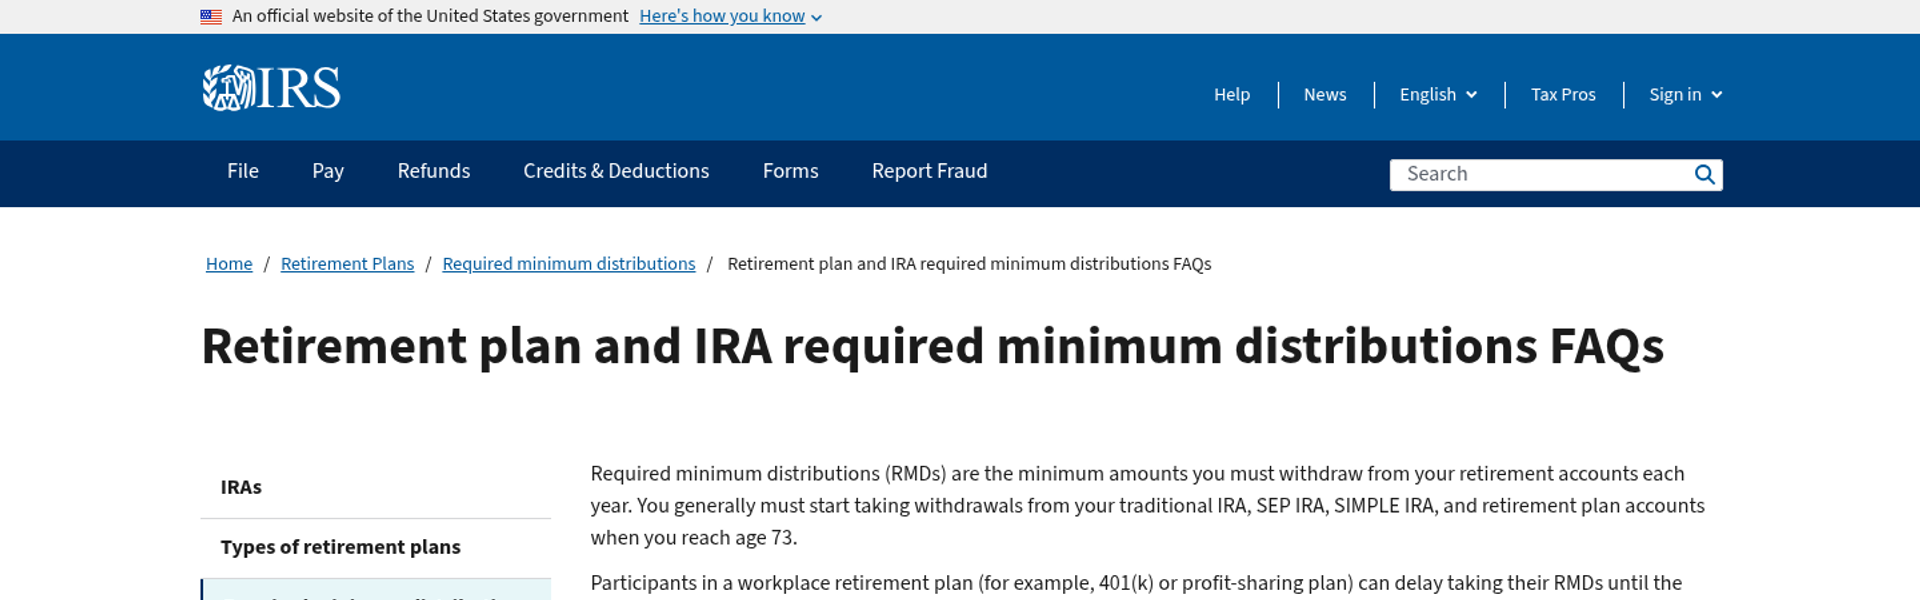
Qualified annuities are also subject to minimum distributions when you reach age 73. That applies to MYGAs and FIAs held inside a qualified account. If you have a large balance and don't plan ahead, those forced withdrawals could push you into a higher tax bracket.
Inheritance is another area worth a close look. Most annuities have a death benefit that passes to named beneficiaries without going through probate, which is a helpful benefit. But the rules around how a beneficiary can receive and stretch those payments can vary between products and between insurance companies. Some FIAs include living benefit riders that also have implications for what gets passed on.
How this annuity fits into your wider estate picture is worth thinking through. If you're leaving money to a spouse, the options are usually more flexible than if you're leaving it to an adult child or a trust. Beneficiary designations on annuities work separately from your will, so they need to stay up to date.
This is actually an area where a tax advisor or financial planner can add value. The laws aren't impossibly complex. But the combinations of account type, beneficiary relationship, and product structure create enough variation to make personalized input worthwhile.
Matching Each Product to the Right Type of Saver
At this point, you have enough context to decide where you land. These two products are not interchangeable, and the right fit usually depends on personality and timing as much as math.
A MYGA tends to work well for a person who wants to know what they will have at the end of a set term. If you are within a few years of retirement, or you already have enough market exposure elsewhere, a rate with no surprises is legitimately helpful. It's also a fit if you find annuity complexity off-putting and want something closer to a certificate of deposit in terms of how it behaves.
A fixed indexed annuity is suited to a different saver. If you have a longer time horizon and want some participation in market growth without direct downside exposure, an FIA gives you that middle ground. You need to be comfortable not knowing what your credit will be each year and willing to read the fine print on caps and participation rates.
| You might lean toward a MYGA if... | You might lean toward an FIA if... |
|---|---|
| You want a fixed, predictable return | You want growth potential above a fixed rate |
| You have a specific savings window in mind | You have a longer accumulation timeline |
| You prefer straightforward product terms | You are comfortable with more product complexity |
| You want to complement existing market investments | You want downside protection with some upside |
It also helps to remember where this fits in your wider income plan. Neither product is meant to hold all of your retirement savings, and life stage matters here. Someone still ten years out has different goals than someone drawing income next year. If you'd like personalized guidance, reading through our client reviews can give you a sense of how we help savers make these decisions.
Making the Call - MYGA, FIA, or Something in Between?
Before committing to either, take a few concrete steps: compare quotes from multiple highly-rated carriers, run the numbers on your surrender period against your liquidity needs, and see if you're holding the annuity in a tax-deferred account - where the built-in tax deferral of an annuity can add less incremental value. A fee-only or fiduciary financial advisor helps you stress-test the assumptions and cut through marketing language that sometimes makes products sound better than they are in practice.
The best annuity is the one you'll still feel confident about in year five of a surrender schedule when the market does something unexpected. Take your time, ask hard questions, and don't sign anything until the answer to "what happens if I need this money early?" is clear to you. You can also read what real clients have to say on our testimonials page to see how others have navigated these decisions.
FAQs
What is the main difference between a MYGA and FIA?
A MYGA locks in a fixed interest rate for a set term, giving you predictable, guaranteed growth. A Fixed Indexed Annuity ties your growth to a market index, offering potential for higher returns but with capped upside and no direct market loss.
Can you lose money with either annuity type?
No. Both MYGAs and FIAs protect your principal. MYGAs guarantee a fixed return, while FIAs include a floor that prevents losses even when the market index performs negatively.
How long are typical surrender charge periods?
Surrender charge periods typically span six to eight years for both MYGAs and FIAs. Most contracts allow a free withdrawal of up to 10% of account value annually, but exceeding that triggers penalty charges.
Are MYGA and FIA gains taxed annually?
No. Both products grow tax-deferred, meaning you only pay taxes when withdrawals are made. Qualified annuities funded with pre-tax money are fully taxable on withdrawal, while only the growth portion of non-qualified annuities is taxed.
Which annuity suits someone nearing retirement?
A MYGA is generally better suited for those nearing retirement, offering simplicity and predictable returns. FIAs better fit savers with longer time horizons who want some market-linked growth potential with downside protection.
With over 25 years of combined experience in the Insurance Industry and excellent custom service, we are your trusted local brokers specializing in all types of insurance solutions.